Mortgage Renewal: How to Compare, Negotiate and Avoid Penalties
The 21-day statement, shopping around, switching lenders and prepayment penalties: how to prepare for your mortgage renewal, according to the FCAC.
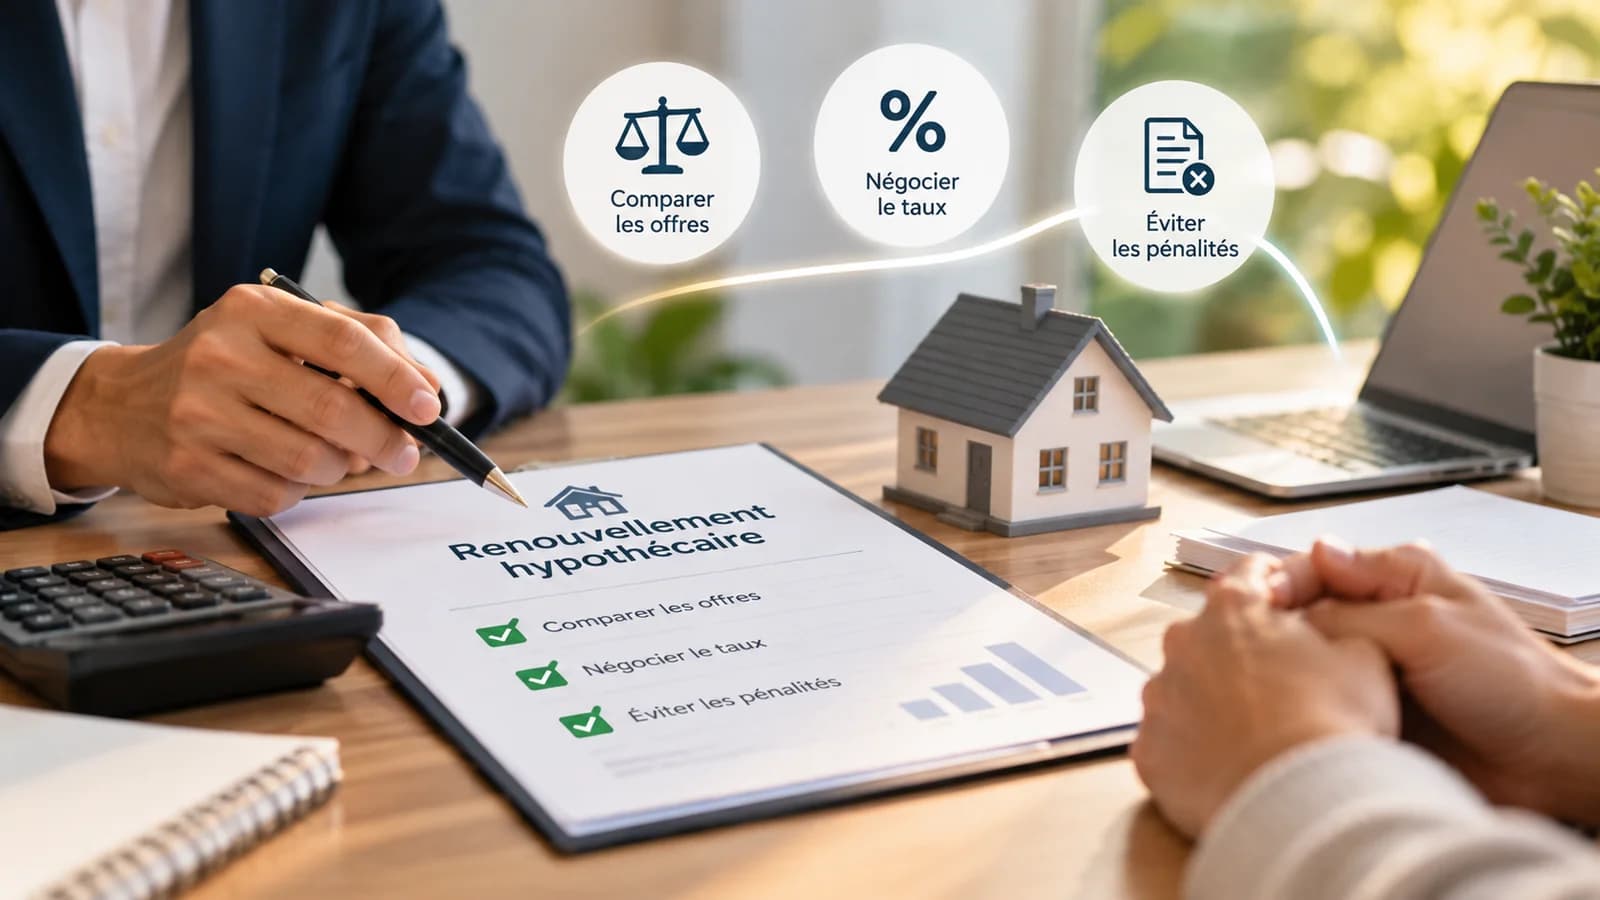
At the end of each term, your mortgage must be renewed, and it is one of the few times you can renegotiate without a penalty. Yet many owners sign the renewal letter without comparing. Here is how to prepare, according to the Financial Consumer Agency of Canada (FCAC).
At a glance
- If your lender is a federally regulated institution, such as a bank, it must send you a renewal statement at least 21 days before the end of the term.
- You don't have to stay with the same lender. The FCAC recommends shopping around a few months before your term ends.
- If you do nothing, your mortgage may renew automatically, without necessarily getting the best rate.
- Switching lenders can involve fees (application, discharge, registration, appraisal). Breaking a contract before the end of the term can trigger a significant penalty.
What is a mortgage renewal?
According to the FCAC (https://www.canada.ca/en/financial-consumer-agency/services/mortgages/renew-mortgage.html), your mortgage contract has a set length, the term, which can range from a few months to five years or more. At the end of each term, you must renew or pay off the mortgage. Most owners renew several times before paying it off completely.
What the renewal statement must include
For a mortgage with a federally regulated institution, the statement must arrive at least 21 days before the end of the term and specify:
- the balance owing on the renewal date;
- the interest rate;
- the payment frequency;
- the term;
- any applicable fees.
The statement must also say that the rate offered will not increase before the renewal date. The lender must also tell you 21 days before the end of the term if it will not renew your mortgage.
How to prepare, step by step
- Note your term's end date and start shopping a few months before, without waiting for your lender's letter.
- Reassess your needs: do you want to increase payments, change their frequency, make extra payments, consolidate debt or review your insurance?
- Ask other lenders and mortgage brokers for offers.
- Negotiate with your current lender using those offers. It may ask to see them.
- Compare the total cost, not just the rate: transfer, appraisal and notary fees if you switch lenders.
Extending your amortization to lower payments comes at a cost: the FCAC notes that the interest you pay can rise by thousands or even tens of thousands of dollars.
Switching lenders: costs to expect
The new lender must approve your application using its own criteria. According to the FCAC, expect:
- the new lender's application fees, such as discharge and registration fees;
- transfer or assignment fees from your current lender;
- appraisal fees, if needed;
- notary or lawyer fees to discharge the old mortgage and register the new one.
Ask the new lender whether it will cover part of these costs. If your mortgage is already insured, tell the new lender so you don't pay mortgage loan insurance twice. A new premium may apply if you increase the amount or extend the amortization.
Renewing early: watch out for penalties
According to the FCAC (https://www.canada.ca/en/financial-consumer-agency/services/mortgages/reduce-prepayment-penalties.html), breaking your contract before the end of the term, for example to get a lower rate or when selling, can trigger a prepayment penalty. It is usually the higher of two amounts: 3 months' interest, or the interest rate differential (IRD).
The FCAC's example: for a $200,000 balance at 6%, with 36 months left and a posted rate of 4% for a 36-month term, 3 months' interest is about $3,000, while the IRD is about $12,000. The higher amount applies, sometimes with administration fees.
To reduce the penalty, the FCAC suggests using your prepayment privileges fully, waiting until the end of the term if the penalty is high, or, if you are buying another property, asking whether your mortgage is portable.
Selling or buying during your term?
Selling before the end of your term can trigger a penalty. Talk to your lender before setting your dates, and factor it into your selling budget. If you are buying another property, being able to port your mortgage can change the math.
Frequently asked questions
When should I receive my mortgage renewal statement?
If your lender is a federally regulated institution, such as a bank, it must send it at least 21 days before the end of the term, according to the FCAC.
Do I have to renew with the same bank?
No. You can transfer your mortgage to another lender, which will have to approve your application. Fees may apply.
What happens if I don't respond to the renewal statement?
Your mortgage may renew automatically for another term, without necessarily getting the best rate. The statement tells you if this is the case.
How is the penalty calculated if I pay off early?
Usually it is the higher of 3 months' interest and the interest rate differential. The method varies by lender; check your contract.
Related reading
Sources, method and limitations
- Financial Consumer Agency of Canada, "Renewing your mortgage" (https://www.canada.ca/en/financial-consumer-agency/services/mortgages/renew-mortgage.html): renewal statement, shopping around, switching lenders.
- FCAC, "Mortgage prepayment penalties" (https://www.canada.ca/en/financial-consumer-agency/services/mortgages/reduce-prepayment-penalties.html): penalty calculation and example.
Équipe Lefrançois is a team of real estate brokers, not mortgage brokers. This article is for information only: it quotes no rates and does not replace advice from a lender or mortgage broker. The rules described apply to federally regulated institutions; other lenders, such as credit unions, may have different rules. Information current as of October 8, 2026.
Is your renewal coming up at the same time as a sale or purchase? Let's talk early to line up the dates: 514-700-1221.
Planning a real estate purchase in Montreal?
Our team can help you find the property that matches your project.
Related content
Pre-Purchase Inspection: What to Do After the Report (Negotiate, Deadlines, Withdraw)
Clause 8.1, notice to the seller within four days, the Amendments form and RBQ-certified inspectors: your options after the inspection, according to the OACIQ.
2026 Rent Increases and the TAL's New Method: What It Means for a Montreal Plex
A 3.1% base percentage, adjustments for taxes, insurance and major work, strict notice deadlines: what duplex and triplex buyers and owners need to know.
Condo, Duplex or House in Montreal: How to Choose Based on Your Budget and Plans
Financing, recurring costs, responsibilities and resale: a practical comparison of condos, owner-occupied plexes and houses for buying in Montreal.